Should you fix or float your mortgage in New Zealand?
Understand fixed and floating mortgage rates, compare possible repayment changes, and prepare for your next refix without trying to predict the market.
Choosing a mortgage rate can feel like being asked to predict the future with hundreds of thousands of dollars at stake.
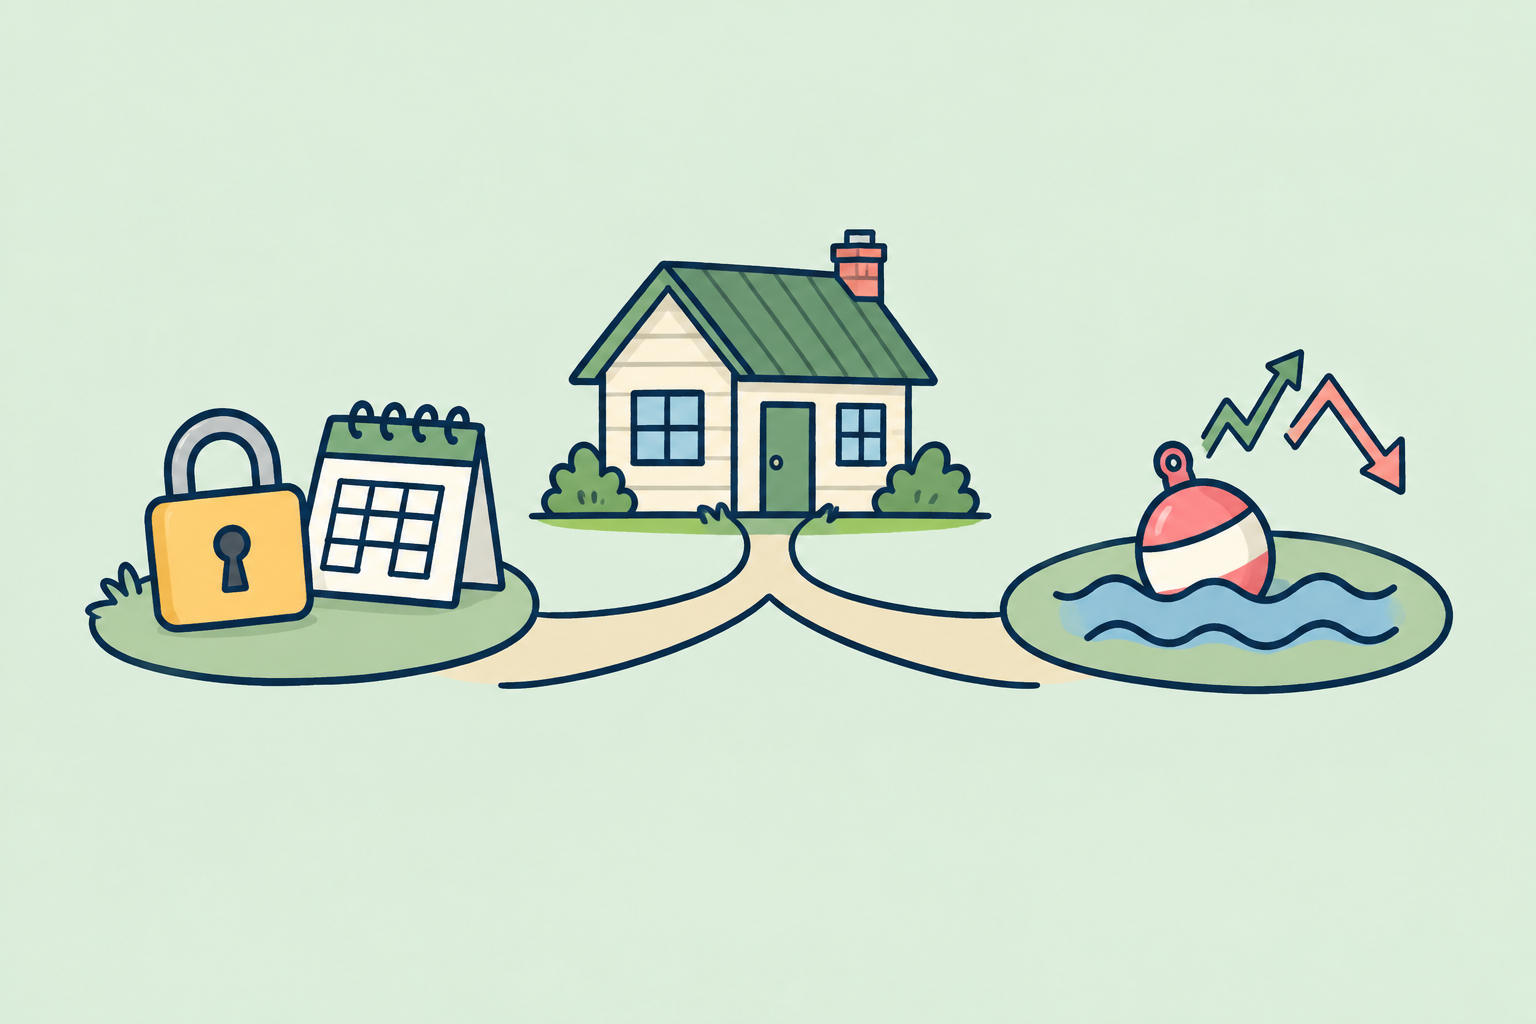
Fix for a short term and rates might rise before you refix. Fix for longer and rates might fall while you are locked in. Stay floating and you keep flexibility, but your repayment can change.
It is no surprise that this decision receives so much attention. The Reserve Bank says around 10 percent of mortgage lending is floating, while about two thirds is fixed and due to be repriced within one year. That means many New Zealand households regularly face the same question.
There is no term that is automatically right for everyone. A useful decision is based on the repayment your household can manage, the flexibility you may need, and what would happen if your plans changed. It is not based only on guessing the next interest rate move.
This article explains the choices and questions involved. It provides general education, not personalised financial advice or a recommendation to select a particular rate.
What fixed and floating actually mean
A fixed mortgage rate stays the same for an agreed period, often from six months to several years. This usually makes the required repayment more predictable during that period.
At the end of the fixed period, you choose another available rate or the loan moves to the floating rate under your lender's terms. Your new repayment is based on the balance, remaining loan term, and interest rate at that time.
A floating rate can change while you hold it. The lender decides its rate based on its funding costs, market conditions, competition, and other factors. Changes to the Official Cash Rate can influence mortgage rates, but a lender does not have to change its floating rate by exactly the same amount or at exactly the same time.
Floating loans normally offer more freedom to increase repayments or make lump sum payments. The exact conditions depend on the lender.
The simplest way to remember the distinction is:
- Fixed provides more repayment certainty for a set period.
- Floating provides more repayment flexibility, but less certainty about the rate.
Neither option protects you from every risk.
Start with the repayment, not the headline rate
A small rate difference can meaningfully change a large mortgage.
Imagine Moana has a $500,000 principal and interest mortgage with 25 years remaining. Using simplified example rates:
- At 5 percent, the repayment would be about $2,923 a month.
- At 6 percent, the repayment would be about $3,222 a month.
- At 7 percent, the repayment would be about $3,534 a month.
Moving from 5 percent to 6 percent adds about $299 a month. Moving from 5 percent to 7 percent adds about $611 a month.
These are illustrative calculations, not current offers or repayment quotes. They assume the rate remains unchanged, payments are monthly, and there are no fees. Your lender will calculate the actual repayment.
The important question for Moana is not only which rate looks cheapest today. She also needs to know whether her household could absorb an extra $300 or $600 a month when the loan next changes.
When a fixed rate may feel more useful
A fixed period may be worth discussing when predictable repayments are important to your household.
For example:
- Your budget has little room for a sudden repayment increase.
- You are temporarily relying on one income.
- You expect childcare, study, health, or other essential costs to increase.
- You prefer knowing the required payment while you build a cash buffer.
- You do not expect to sell, refinance, or repay a large amount during the fixed period.
Fixing does not mean the mortgage is predictable forever. It moves the next rate decision to the end of the fixed period.
It can also reduce flexibility. A lender may limit how much extra you can repay without a cost. If you sell the property, refinance, restructure the loan, or repay more than the permitted amount, an early repayment charge may apply.
Do not assume the limit is the same at every bank. Ask your lender for the rules that apply to your loan.
When floating may feel more useful
A floating portion may be worth discussing when flexibility matters more than a fixed repayment.
For example:
- You expect a bonus, inheritance, property sale, or other lump sum.
- Your income changes and you want to make larger payments during strong months.
- You may sell or refinance soon.
- You want to move to a fixed rate later without breaking an existing fixed term.
- You are using an offset or revolving credit structure.
The tradeoff is that the rate and repayment can change. Floating rates may also be higher than available fixed rates at a particular time.
Flexibility only has value when you are likely to use it. Paying a higher floating rate for years without making extra repayments may cost more than expected.
How long should you fix for?
The fixed term decides how soon you will face another rate decision.
A shorter fixed term
A six month or one year term brings the next refix date closer. This may preserve more near term flexibility, but it also exposes you to the rate available sooner.
Before choosing it, ask:
- Could the household manage a higher repayment at the next refix?
- Is there a known change coming, such as moving home or receiving a lump sum?
- Are any cash incentives, legal costs, or loan fees tied to remaining with the lender?
- Will you have time to review the mortgage again before the term ends?
A longer fixed term
A two year or longer term provides certainty for more time. That may help a household plan, but it keeps the loan committed to the agreed rate for longer.
Before choosing it, ask:
- How likely are you to sell, refinance, or change the loan structure?
- Would you want to make substantial extra repayments?
- What costs could apply if your circumstances changed?
- Is the certainty worth the difference between this rate and shorter alternatives?
A longer term is not automatically safer. It reduces one kind of uncertainty while increasing the time during which changing the loan may have a cost.
Compare the same two years, not just today’s rate
Suppose Moana is comparing two illustrative offers for her $500,000 mortgage with 25 years remaining: 5 percent fixed for two years, or 5.5 percent fixed for one year before choosing another rate.
At 5 percent, her monthly repayment would be about $2,923. At 5.5 percent, it would initially be about $3,070. The shorter option costs more at first, so the rate in the second year would need to be lower to make up the difference.
In this example, the second year rate would need to be about 4.48 percent for the two options to produce roughly the same total interest over two years, about $49,000. Above that rate, the shorter option would cost more in interest. Below it, it would cost less.
These are calculated examples, not current offers or forecasts. They assume monthly principal and interest repayments, no fees or extra payments, and a repayment recalculated over the remaining 24 years after the first year. Total interest is not the same as total repayments, since repayments also reduce the debt. Your lender can compare the actual payments, interest and remaining balance for your offers.
The question becomes, “How much would rates need to fall for this option to cost less?” rather than simply, “Will rates fall?” Neither question tells you what will actually happen.
Would more certainty help you sleep?
Opes Partners also discusses a simple sleep test: how comfortable are you with your mortgage payment changing sooner?
Use Cash Flow in Fireball to review recent income and spending, then compare the lender’s repayment quotes with the room left for other commitments. If an increase would leave very little breathing room, certainty may matter more to you than the possibility of a cheaper rate later. If you have a buffer, you may feel more comfortable with an earlier refix. That is a preference to discuss with your lender or adviser, not a guarantee that either term will be cheaper.
You do not have to choose one term for the whole mortgage
Some borrowers divide the mortgage into portions. This is often called splitting or staggering the loan.
For illustration, a $500,000 mortgage could be divided into:
- $300,000 fixed for one year.
- $150,000 fixed for two years.
- $50,000 floating or offset.
This is an example, not a suggested allocation.
Only part of the mortgage reaches the end of its fixed period at one time. The floating portion may allow extra repayments or work with an eligible offset arrangement.
Splitting does not guarantee a lower cost. It can create several repayment amounts and refix dates to manage. It also means some portions may be on higher rates while others are on lower rates.
The benefit is diversification of timing, not certainty that the structure will beat every alternative.
If accessible savings are part of the plan, read Is a mortgage offset account worth it in New Zealand? before deciding how large a floating or offset portion should be.
What happens when your fixed term ends?
Your lender will normally contact you before the fixed period ends. If you do nothing, the loan may move to the lender's applicable floating rate. Confirm the process and timing with your lender because the terms differ.
Use the refix as an opportunity to review more than the interest rate:
- Check the remaining balance and loan term.
- Compare the repayment under each rate option.
- Review whether your income or essential spending has changed.
- Decide whether you expect extra repayments or a lump sum.
- Check whether the loan structure still fits your savings and plans.
- Ask about fees, discounts, cash contributions, and conditions.
- Compare another lender only after including switching costs and possible repayment obligations.
Some lenders let eligible borrowers lock a fixed rate before the existing term ends. For example, BNZ says eligible customers may be able to lock a rate up to 60 days before expiry. A rate lock can have conditions or a cost if you later change your choice. Check the current rules rather than assuming a rate shown today will remain available.
Understand break costs before fixing
A fixed rate is an agreement for a defined period. Ending or changing it early may produce an early repayment charge, often called a break cost.
Consumer Protection says a lender can charge for costs or losses created by breaking a fixed mortgage when the contract allows it. The calculation can be complicated and the amount depends on the loan, remaining fixed period, and market conditions.
A break cost is not something you can calculate reliably from a general article. Ask the lender for a written quote before selling, refinancing, restructuring, or making a large repayment.
Also check for other costs. Moving banks can involve legal work, valuation costs, discharge fees, or repayment of a cash contribution received when the mortgage began. A lower advertised rate does not automatically cover those expenses.
Do not treat an advertised rate as your final offer
The rate displayed publicly may have eligibility conditions. A special rate could depend on your deposit or equity, lending amount, salary payments, account package, property use, or other requirements.
Ask each lender to confirm:
- The rate available for your actual loan.
- Any low equity premium or margin.
- Establishment, account, valuation, or legal costs.
- The required repayment and repayment frequency.
- How much extra you may repay without an early repayment charge.
- Whether the offer includes a cash contribution and what happens if you leave early.
- How long the quoted rate remains available.
Compare the complete arrangement, not only the largest number in an advertisement.
Use three scenarios instead of one prediction
Nobody can promise which mortgage term will be cheapest after the fact. A more practical approach is to test what your household would experience if rates were lower, similar, or higher at the next refix.
For each option, record:
- The repayment during the chosen term.
- The repayment if the future rate were one percentage point higher.
- The repayment if the future rate were two percentage points higher.
- The cash you would still keep for emergencies.
- Any expected lump sum or change in income.
- What it may cost to change the loan early.
The aim is not to forecast the exact rate. It is to discover which outcomes your finances could handle.
If a modest increase would leave the account short before payday, that is important information. The decision may need to focus on repayment resilience, reducing other commitments, building a buffer, or discussing the structure with the lender rather than chasing the lowest possible rate.
How Fireball can help you prepare
Fireball does not recommend a mortgage rate or decide whether you should fix, float, or split your loan. Your lender performs the official repayment calculation, and personalised mortgage advice should come from an appropriately qualified adviser.
Fireball can help you bring the information around the decision together:
- View advertised New Zealand home loan rates in Markets as a starting point for comparison, then confirm your actual offer with the lender.
- Include your property and mortgage in Net Worth so you can see the debt alongside your other assets and liabilities.
- Review Cash Flow to understand recognised income and categorised spending across recent months.
- Review recurring mortgage payments and other commitments that compete for the same income.
- Use the account forecast for eligible connected accounts to see whether expected activity may leave a balance low before payday.
- Use Budget to test whether a higher repayment would still leave enough for essentials and planned costs.
- Keep emergency savings visible through a Save up goal rather than quietly treating the full account balance as spare money.
Fireball is most useful here as a reality check. A repayment may look affordable in isolation but feel very different when rates, insurance, food, childcare, and annual bills share the same cash flow.
A simple refix routine
Start several weeks before the fixed term ends, using the notice period offered by your lender.
First, understand your position
Confirm the balance, remaining loan term, current repayment, fixed expiry date, and any plans to sell or make a lump sum payment.
Next, review your actual cash flow
Use several ordinary months rather than one unusually cheap or expensive month. Include annual and seasonal costs that are easy to overlook.
Then, compare complete options
For each rate or split, write down the repayment, fixed period, flexibility, fees, and what happens if you change the loan early.
Finally, ask for a personalised quote
Confirm the figures and conditions with the lender. If you want a recommendation based on your circumstances, speak with a licensed mortgage adviser and ask how they are paid and which lenders they consider.
Common questions
Is it better to fix for one year or two years?
Neither term is always better. Compare the rate, repayment certainty, how soon you may need to change the loan, and whether you could manage the repayment available at the next refix. The cheaper choice can only be known afterwards.
Should I wait on a floating rate for fixed rates to fall?
Waiting is a decision to pay the floating rate while accepting that fixed rates may rise, fall, or remain similar. Compare the extra cost of waiting with the possible benefit, and consider whether you need flexibility during that time. Do not rely on a rate prediction as if it were certain.
Can I refix before my current term ends?
Some lenders allow eligible customers to select or lock a new fixed rate before expiry. The available period, rate, and conditions vary. Ask what happens if rates move or you change your mind after locking.
Can I make extra repayments on a fixed mortgage?
Often, but the amount and frequency allowed without an early repayment charge depend on the lender and loan agreement. Get confirmation before increasing payments or making a lump sum.
Does a fixed mortgage repayment always stay the same?
The interest rate stays fixed for the agreed period. Your required payment is usually predictable, but changes to the loan, repayment arrangement, fees, or other contract terms can affect what you pay. Confirm the payment shown in your loan documents.
Is a mortgage adviser required?
You can discuss options directly with a lender. A licensed mortgage adviser can provide personalised advice and may compare several lenders. Ask whether the adviser charges you, receives commission, and which lenders they do and do not consider.
Choose a structure you can live with
The best result is not necessarily the term that later turns out to have the lowest rate. A mortgage structure also needs to work when bills arrive, income changes, or life does not follow the forecast.
Fixing can provide certainty. Floating can provide flexibility. Splitting can spread the timing of future decisions. Each benefit comes with a tradeoff.
Use real household cash flow, test uncomfortable scenarios, and understand the cost of changing course. Then confirm the available rates and contract terms with the lender or seek personalised advice from a licensed mortgage adviser.
Sources
- Reserve Bank information about the New Zealand banking sector
- Reserve Bank mortgage lending statistics
- Consumer Protection guidance on mortgages and home loans
- Sorted guide to mortgage types
- Sorted guide to managing a mortgage
- BNZ guidance on refixing a home loan
- Financial Markets Authority guidance on mortgage advice
This article provides general information only. It is not personalised financial advice and does not recommend a lender, mortgage rate, fixed period, or loan structure. Rates, fees, lending criteria, and contract terms can change. Confirm current information with the lender and consider licensed financial advice before changing your home loan.
Make the next money decision calmer
Turn what you just read into a plan you can track, adjust, and actually live with. Explore our free financial calculators or see how Fireball brings your finances together.