✨ Updates
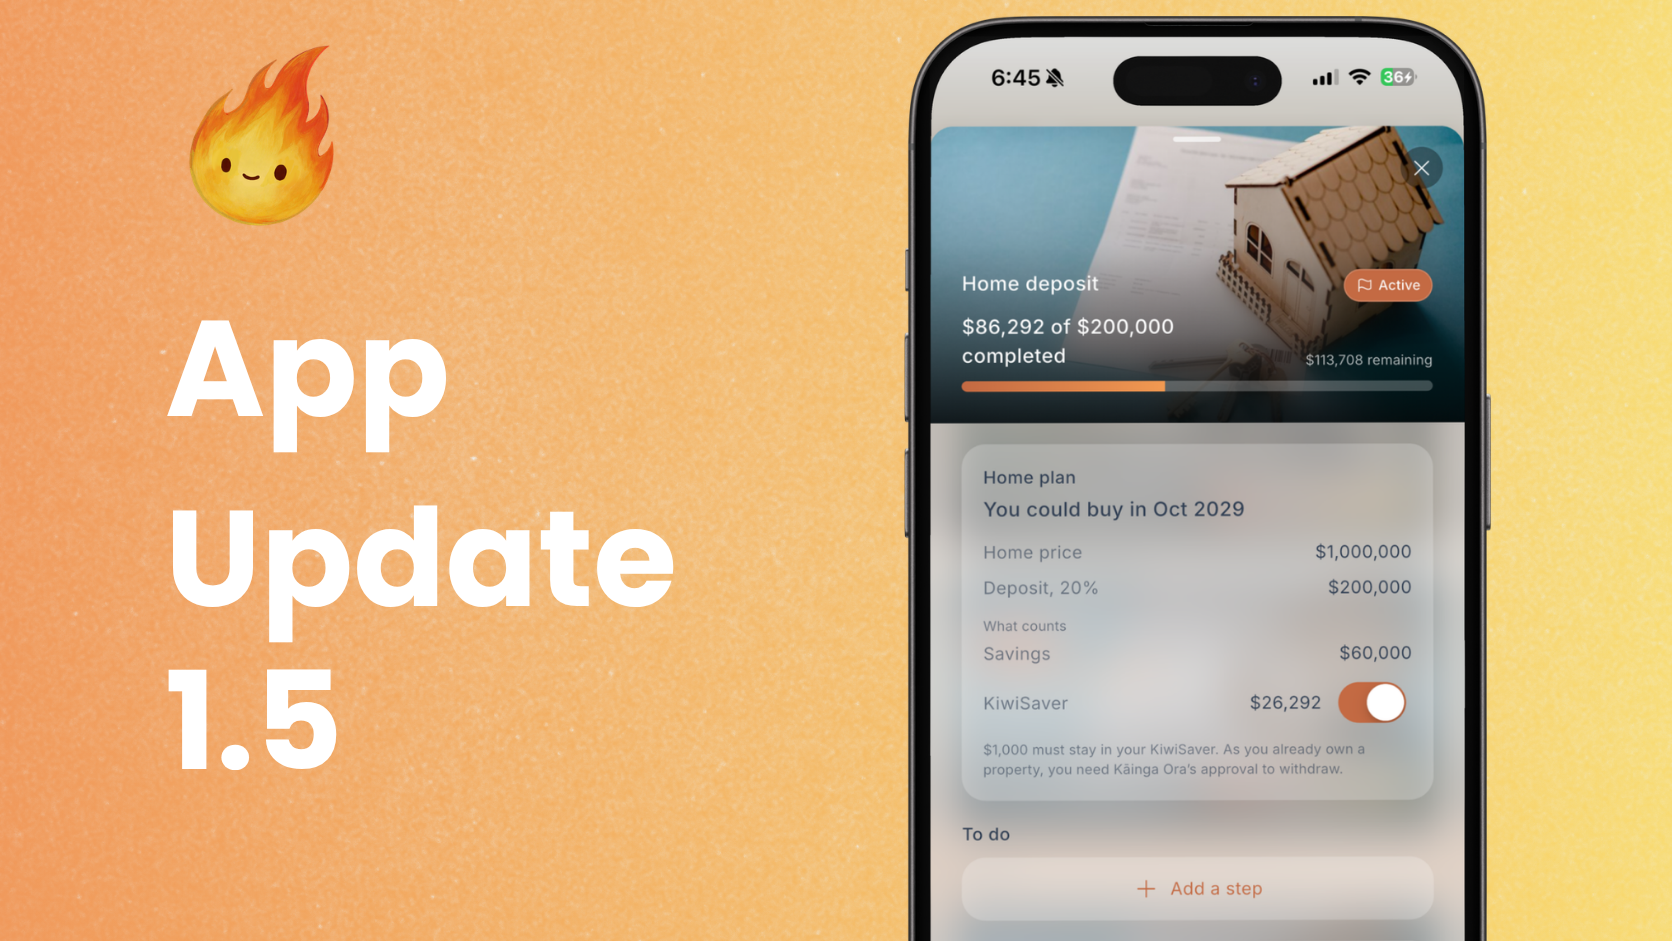
What's new in Fireball 1.5: Family, your first home and your colour
Fireball 1.5 brings a Family plan, first home deposit goals, six accent colours, smarter budgets, better imports and an upgraded Ask Fireball.
Field notes from the team building Fireball.
Start with the money topic closest to what you are working on.
53 articles
Fireball 1.5 brings a Family plan, first home deposit goals, six accent colours, smarter budgets, better imports and an upgraded Ask Fireball.
The KiwiSaver contribution rates you can choose, what each one takes from your pay, and how to decide between the 3.5% default and a higher rate.
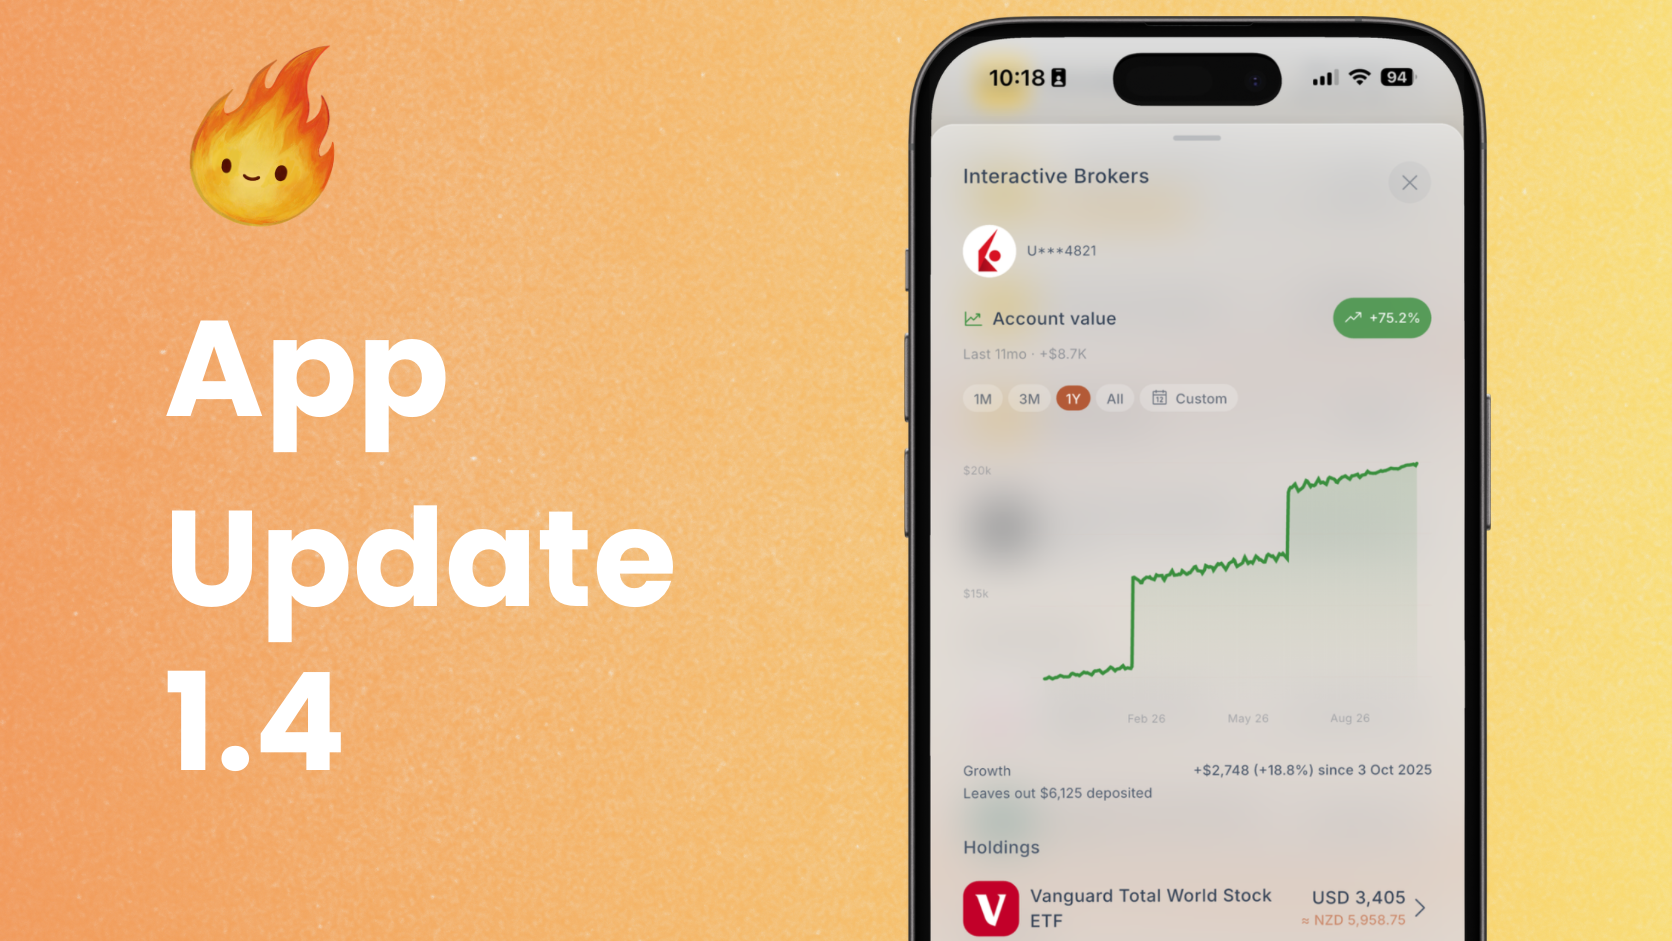
Fireball 1.4.0 brings Interactive Brokers, joint account shares, clearer paybacks and richer savings goals together for a clearer picture of your money.
Moving from PocketSmith? Bring your categories, transactions, notes and rules into Fireball, then build a budget that fits your life now.
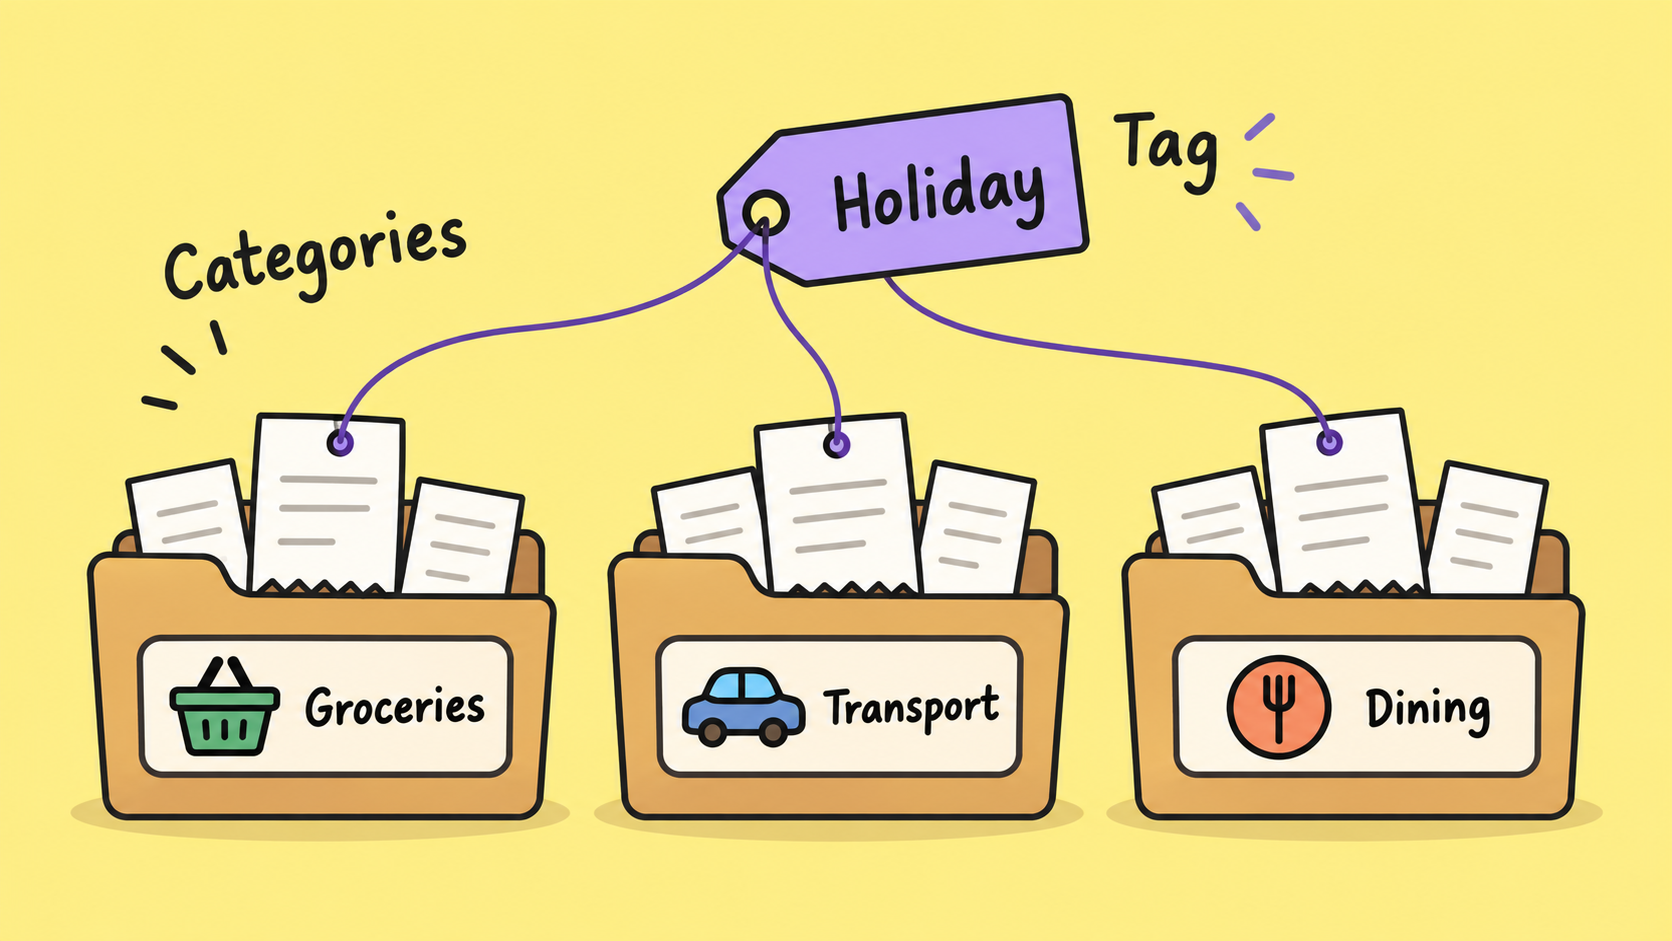
Categories tell you what money was for. Tags tell you what it was part of. Learn when to use each, with simple examples and a quick test you can apply to any transaction.
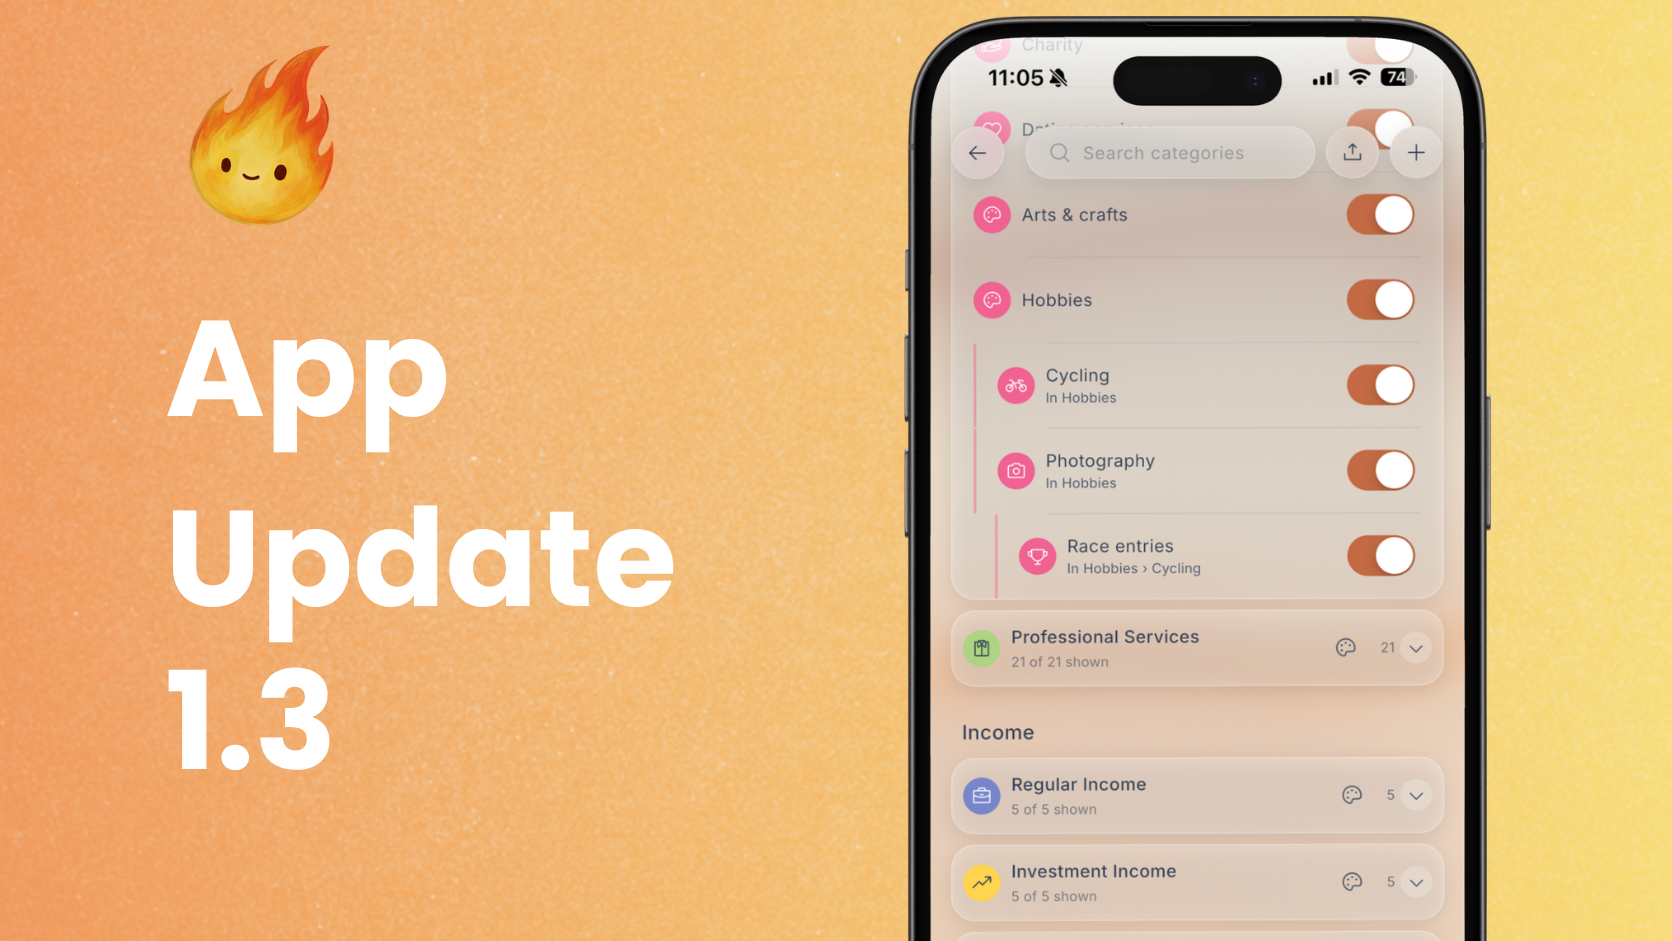
Fireball 1.3 lets you nest and organise your own categories, bring your categories and rules across from PocketSmith, roll budgets over and see your tags in Insights.
Age can provide a useful money checkpoint, but your goals, costs and stage of life matter more than a single savings number.
A new role can improve your prospects, but the first pay and the costs around a change can still affect your cash flow. Plan the transition before you resign.
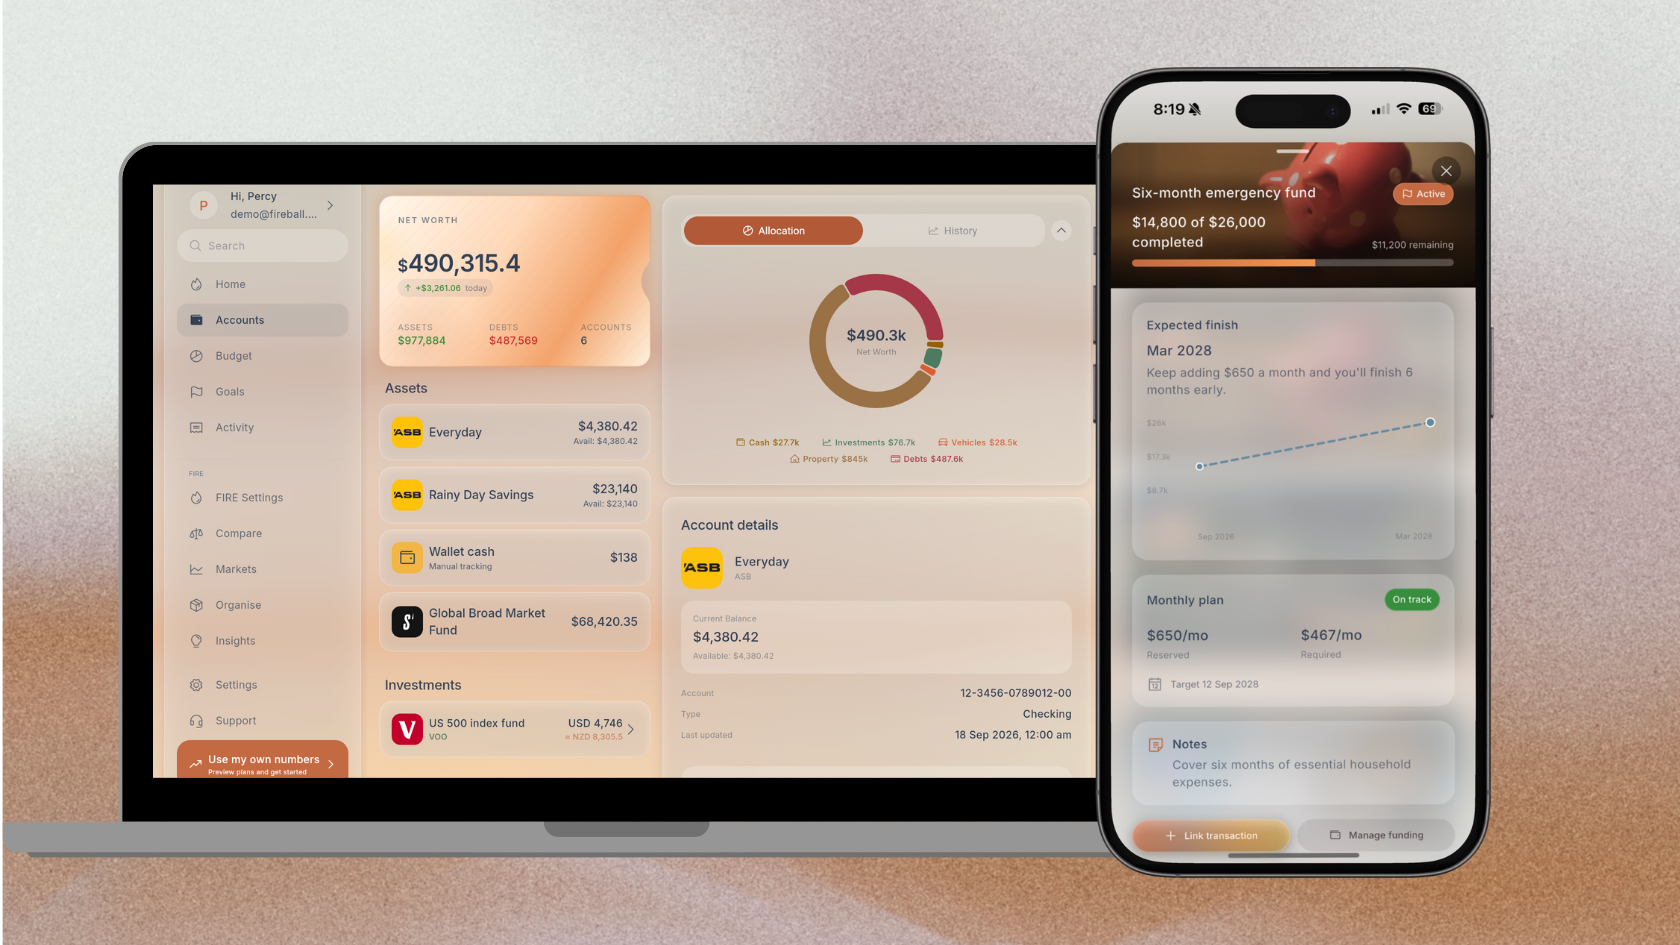
Use Fireball in your browser to connect your financial picture, organise transactions, build a budget and explore your path to financial independence on a larger screen.
Ten things to check before you choose a budgeting app in New Zealand, from NZ bank feeds and automatic categorisation to KiwiSaver, useful insights, price and your data.
Fireball and YNAB compared for New Zealand on bank connections, budgeting style, KiwiSaver and FIRE planning, mortgages, sharing and price, with who each app suits.
Equal payments do not always create equal pressure. Compare practical ways to split household bills, protect personal spending and plan together in Fireball.
Plan for the income change, not just the baby purchases. Use your actual cash flow to prepare for paid leave, unpaid time and returning to work.
Five budgeting apps compared for couples in New Zealand, covering separate logins, joint accounts, shared bills and price, with who each one suits best.
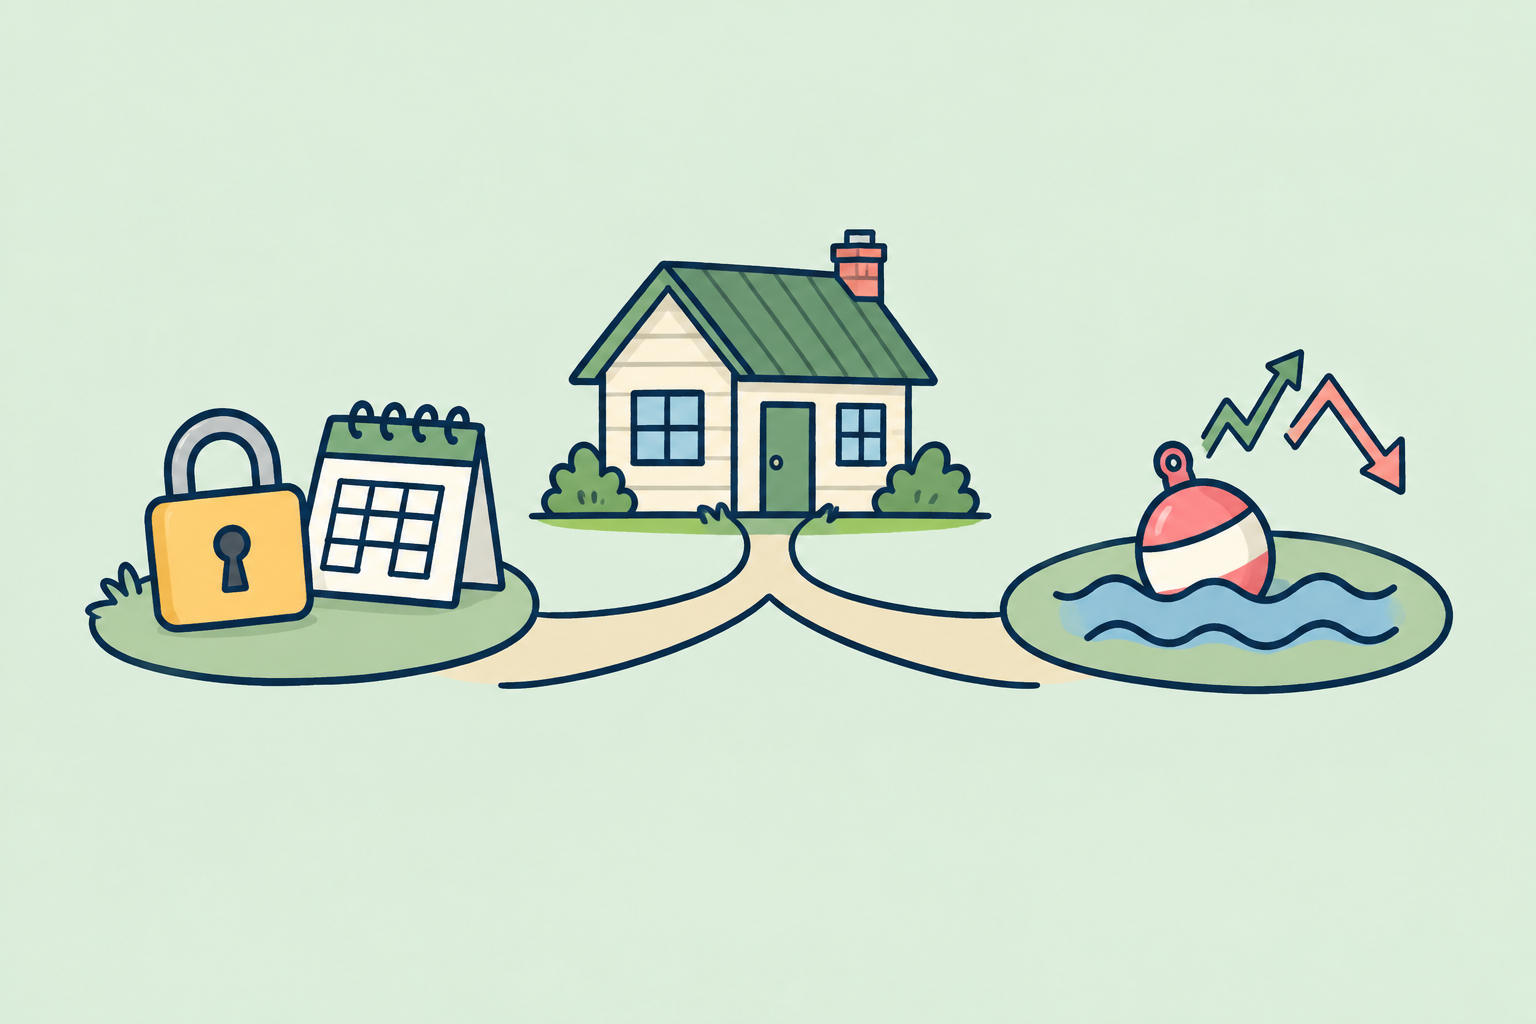
Understand fixed and floating mortgage rates, compare possible repayment changes, and prepare for your next refix without trying to predict the market.
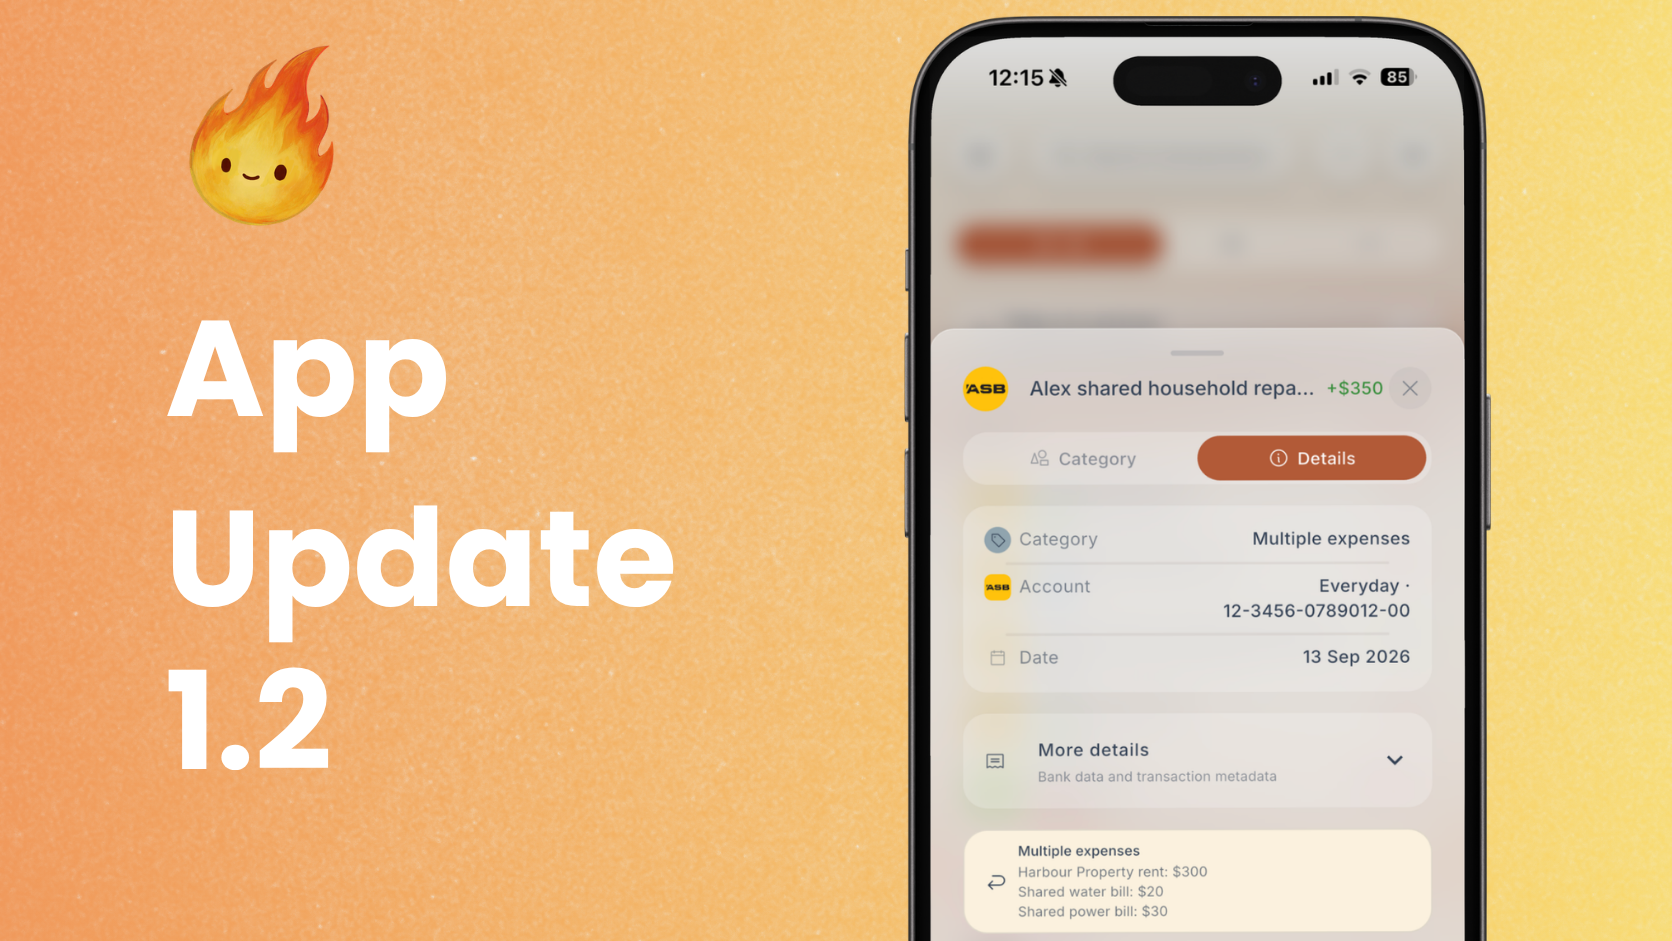
Fireball 1.2 adds a useful Free Plan, manual bank tracking, Afterpay support, smarter refunds, stronger syncing and faster everyday screens.
Compare nine realistic ways to earn extra money in New Zealand, including the time, costs and risks that determine what you actually keep.
Learn how mortgage offset accounts work in New Zealand, what they may save, and when an ordinary savings account or another loan structure may suit you better.
Compare KiwiSaver balanced and S&P 500 funds by fees, investment mix, transaction costs and long term returns in New Zealand.
Your bank balance is not necessarily yours to spend. See what to protect before payday and how Fireball calculates what may be safe to use.
Six apps that track net worth in New Zealand compared on KiwiSaver, property and mortgages, bank feeds and price, with who each one suits and where each falls short.
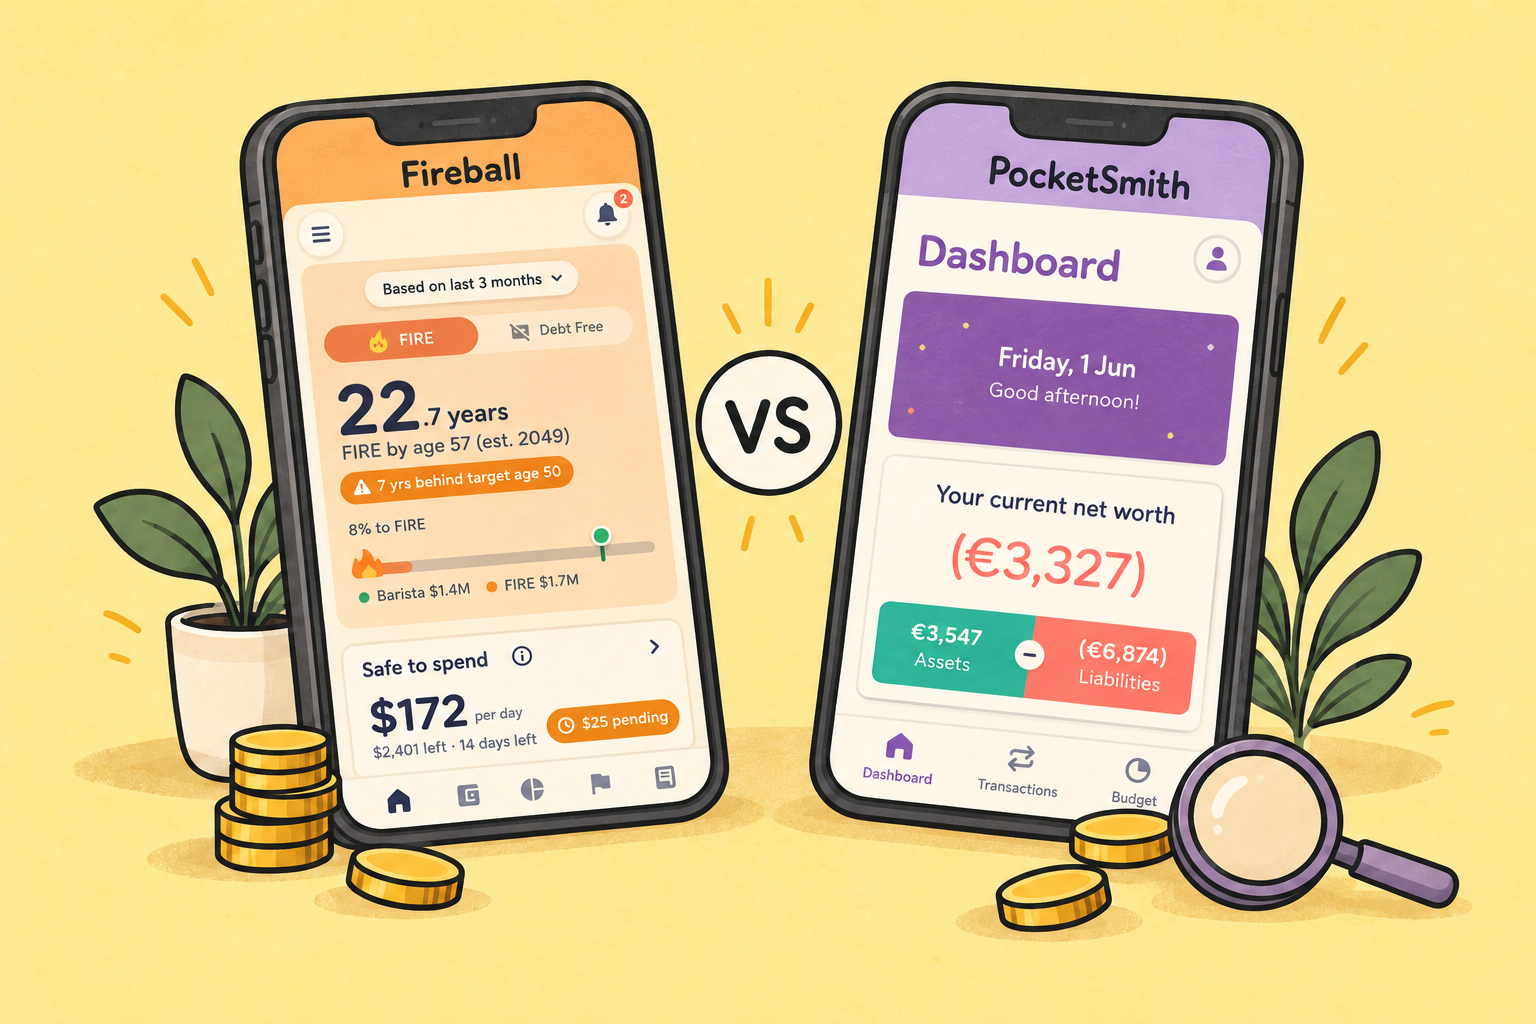
Compare Fireball and PocketSmith for NZ: budgeting styles, smart categorisation, forecasting, FIRE and KiwiSaver, mobile apps, sharing and price.
Renting can cost less today while buying can offer stability and build equity. Compare your monthly affordability gap and the full cost of each option.
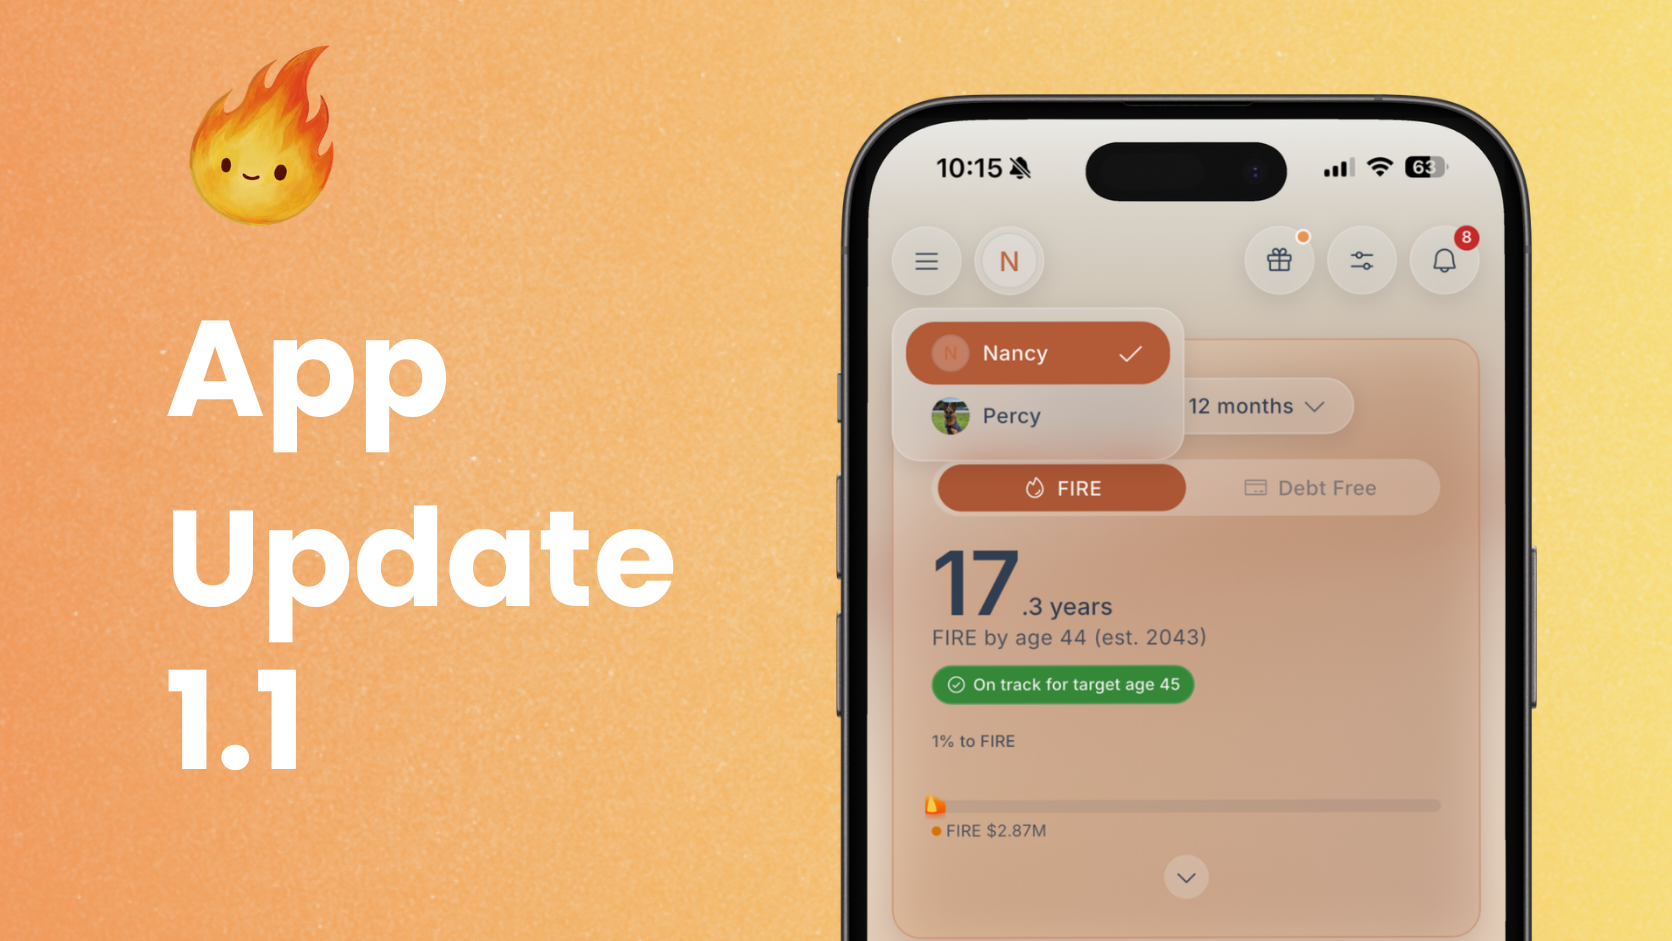
Fireball 1.1 adds shared finances, market tools, Ask Fireball attachments, home loan comparisons, widgets, reminders and clearer organisation.
See how Fireball helps you organise recurring bills, understand rising costs and spot a possible account shortfall before the next payday.
A realistic New Zealand guide to using Fireball to plan around a smaller income, protect essential costs and see problems before payday.
Learn how house deposits work in New Zealand, why 20 percent is common, when a smaller deposit may be possible, and what else to budget for.
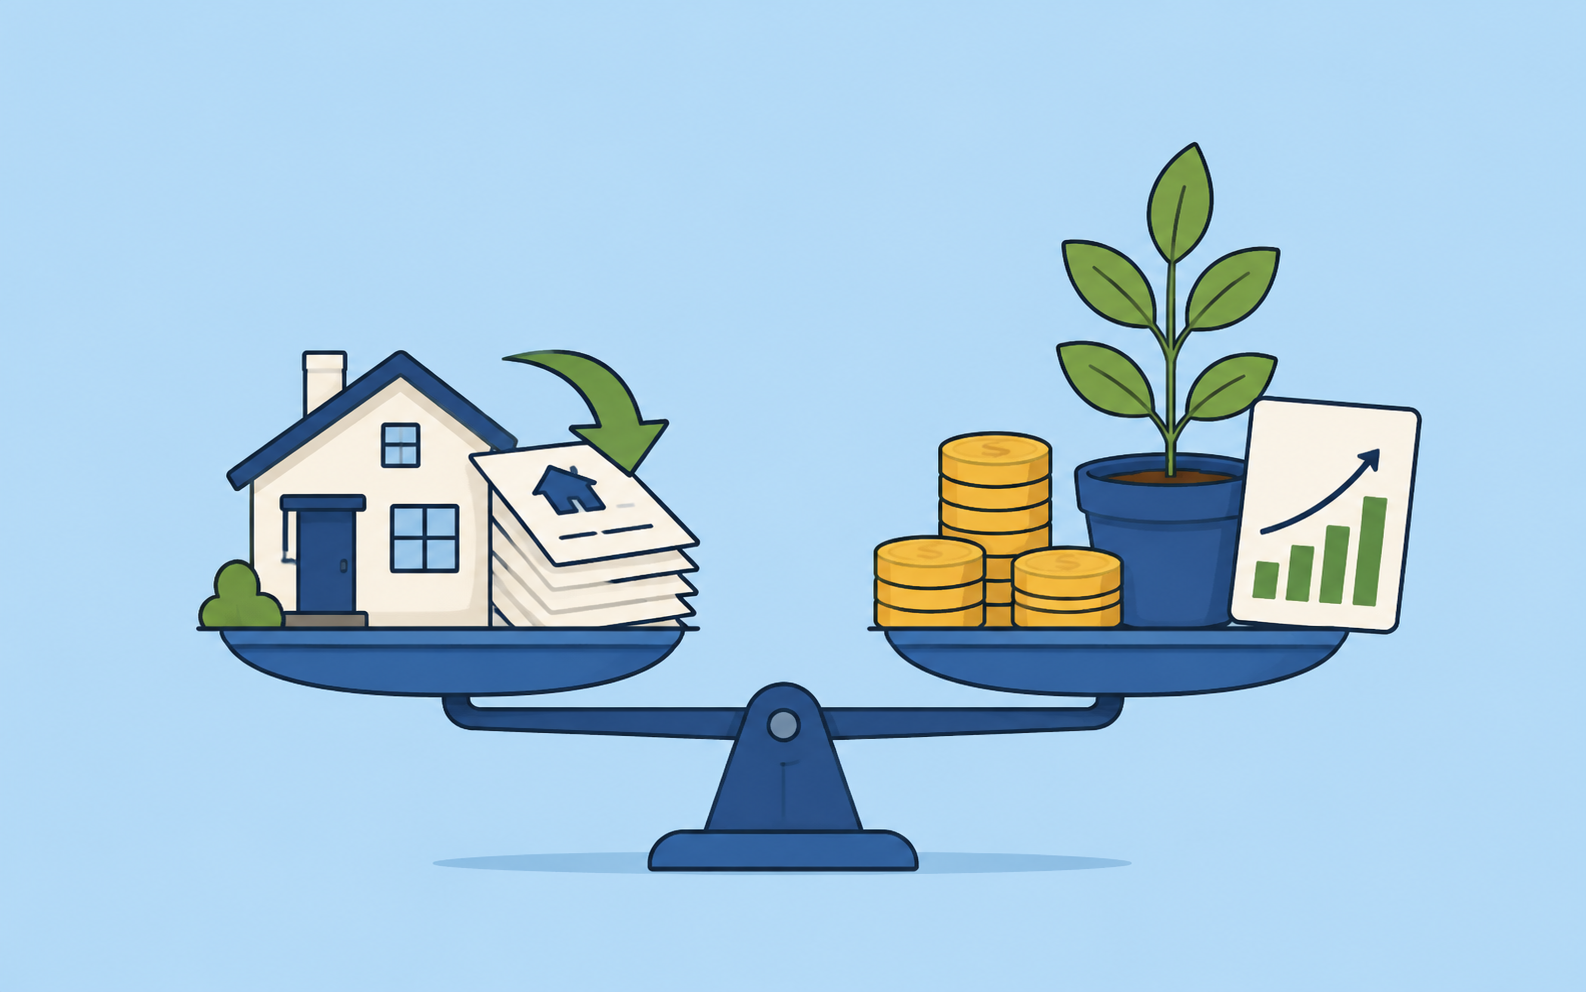
Compare extra mortgage repayments with investing, understand the real tradeoffs, and choose an approach that fits your risk, timeframe and goals.
Learn what happens to KiwiSaver at 65, whether you need to withdraw it, how contributions change, and how to turn a balance into retirement income.
Learn when an extra student loan payment may help, when other goals may deserve priority, and how moving overseas changes the decision.
Wondering whether you have enough saved for your age? Learn what to count, why generic milestones can mislead, and how to set a target that fits your life in New Zealand.
Moving money into a savings account can feel like progress, but it does not tell you how much you kept. Learn how to measure your real savings.
Work out how much you may need to retire in New Zealand by starting with your future spending, then allowing for NZ Super, KiwiSaver, housing and other income.
A changing income does not make budgeting impossible. Set a dependable baseline, forecast recurring income and prepare for possible low balances.
A large KiwiSaver balance can still leave an early retirement gap. See how Fireball connects accessible investments, KiwiSaver and NZ Super.
A side by side comparison of seven budgeting and personal finance apps available in New Zealand, with who each one suits best and where each falls short.
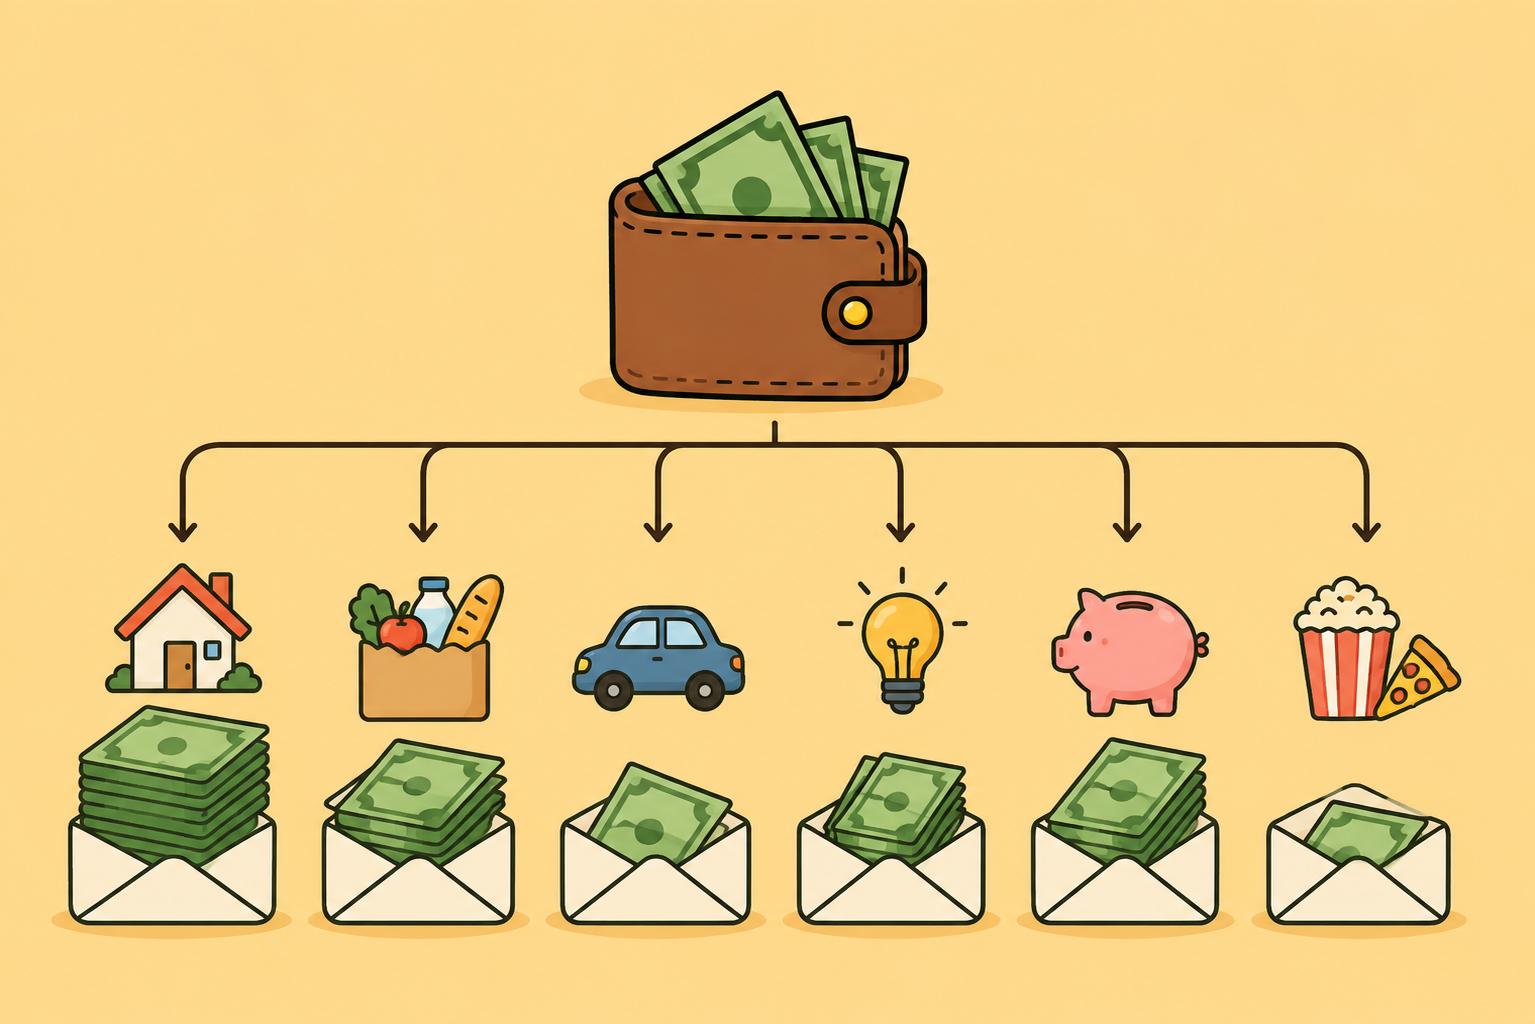
Zero-based budgeting can help you take control of your money, but it doesn’t have to be rigid. Learn how Fireball makes it easier to plan, adjust and stay on track.
Why do we keep buying things we don't really need? Discover how emotions, habits and modern marketing shape our spending, and how to make more intentional money decisions.
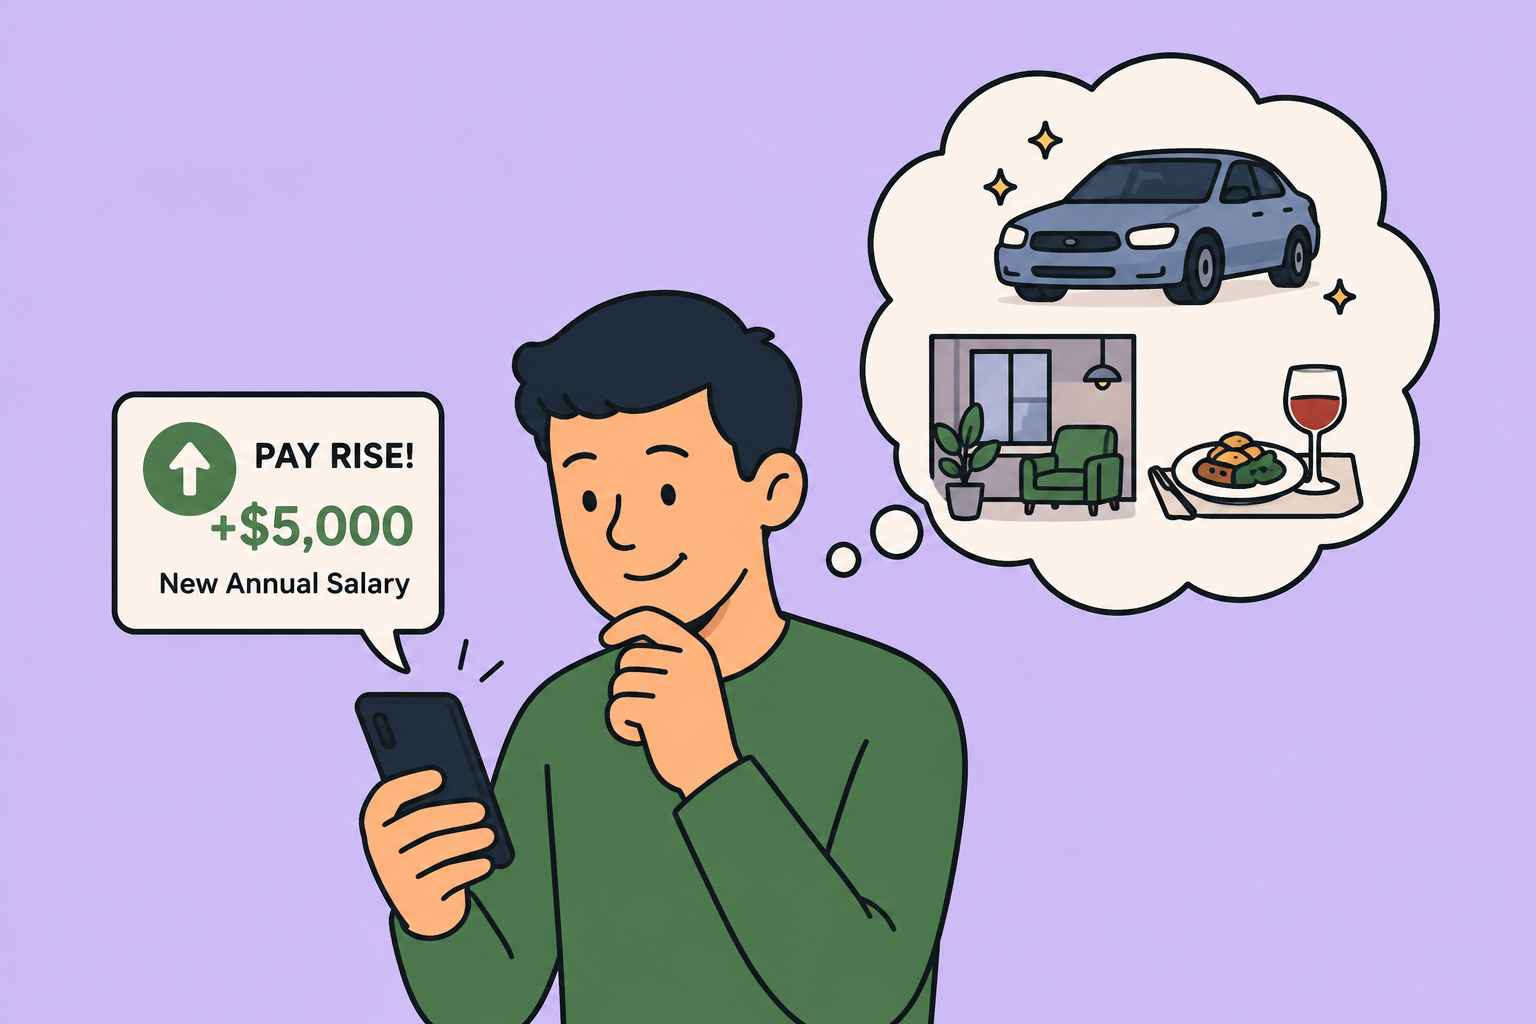
Earning more doesn't guarantee you'll feel richer. Learn why lifestyle inflation happens, how small spending habits quietly absorb pay rises.
The best financial plan isn't the one that impresses strangers. It's the one that helps you build a life that feels like your own.
Wondering how much you should keep in your emergency fund? Learn how much to save, why the "3 to 6 months" rule isn't right for everyone, and how to build an emergency fund that gives you real peace of mind.
Most budgets don't fail because people lack discipline. They fail because they're too rigid for real life. Learn why budgets fall apart, and how a more flexible approach can help you build habits that actually last.
Lean FIRE and Fat FIRE are not about who is better with money. They are two different ways to think about financial independence.
Wondering how much you should save each month? The answer isn't a magic percentage. Learn how to build a realistic savings habit, set achievable goals and create a plan that fits your life.
Learn the difference between Single Budget and Category Budgeting, and discover which budgeting style best matches your spending habits and financial goals
Keeping cash feels safe, but too much can slow your progress. Here’s how investing fits into long-term wealth building.
New to budgeting? This guide will help you understand the basics, choose a budgeting method that suits you, and build habits that last.
Choose joint, separate or hybrid accounts, split shared costs fairly, set shared goals and build a couples budget that both partners can maintain.
42% of New Zealanders carry credit card debt. Most know they have it, know the interest is high, and still find it hard to shift. Here's why the balance barely moves, and what actually helps.
At some point most people look at their bank account and wonder where it went. Not because they spent on anything obvious. It just went. Here's why that happens and what to do about it.
Most people don't overspend on anything obvious. The money just goes. Flex budgeting gives you one number to watch each month — what you have left after everything important is already covered.
Compare Barista FIRE and Coast FIRE in New Zealand, see how part-time income changes your target, and understand how KiwiSaver and NZ Super affect the plan.
Calculate your FIRE number using real spending, accessible investments, KiwiSaver, NZ Super and housing, then turn the estimate into a practical NZ plan.