Fireball vs PocketSmith (2026): Which Money App Is Right for You?
Compare Fireball and PocketSmith for NZ: budgeting styles, smart categorisation, forecasting, FIRE and KiwiSaver, mobile apps, sharing and price.
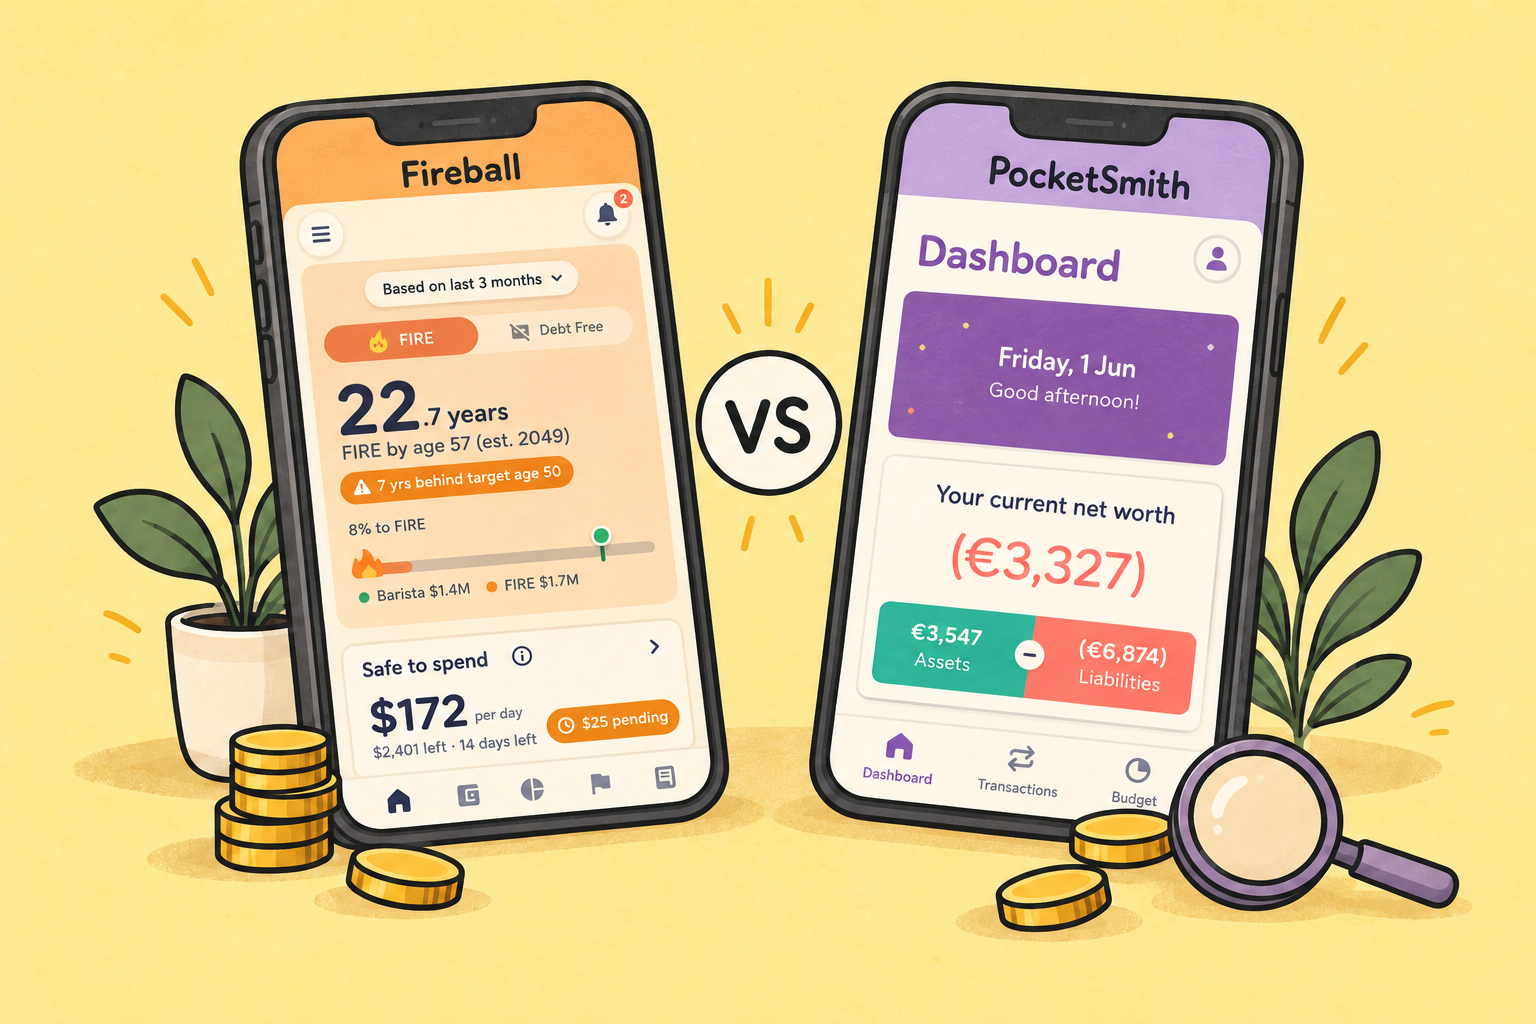
PocketSmith suits people who want detailed calendar based forecasts and accounts across countries, with limits depending on the plan. Fireball suits New Zealanders who want Single, Category or Flex budgeting, categorisation assistance to reduce repeated sorting, and supported local bank feeds on Paid. Dedicated FIRE projections add KiwiSaver and NZ Super assumptions when you want to plan further ahead.
Disclosure: Fireball publishes this comparison and is one of the apps compared. This is general information, not personal financial advice.
How we compared: We used Fireball product documentation and PocketSmith’s official pricing, feature and help pages. The focus is everyday budgeting in New Zealand, forecasting, mobile access and retirement planning. Sources were reviewed on 19 October 2026. Examples are illustrative, rather than results from a controlled test. Confirm your billing currency and current plan terms before subscribing.
Fireball vs PocketSmith at a glance
| Fireball | PocketSmith | |
|---|---|---|
| Best known for | Budgeting tied to a New Zealand FIRE plan | Calendar based cash flow forecasting |
| Budgeting styles | Single, Category or Flex, with optional zero based planning | Customisable category budgets and calendar forecasts; supports several budgeting approaches |
| NZ bank feeds | Yes, through Akahu, unlimited on Paid | Yes, from 6 banks on Foundation to unlimited on Fortune |
| Categorisation help | Rules, confirmed history, reviewed merchants and optional AI suggestions on Paid, with approval | Bank feed categorisation, category rules and filters |
| FIRE number and date | Calculated for you, with a 5,000 outcome stress test | Build it yourself from forecast balances |
| KiwiSaver and NZ Super | Built into the plan | Track KiwiSaver as an account |
| Forecasting | Account balances 3 to 30 days ahead, plus a long term FIRE projection | 6 months free, up to 60 years on Fortune |
| Safe to spend | Safe to Spend protects future bills, goals and chosen debt payments | Safe Balance does not count future budgets |
| Mobile | The full app on iPhone and Android, plus nine widgets | Mobile apps are companions to the web app |
| AI | Ask Fireball built into Paid | Connect your own AI assistant through its MCP server |
| Sharing | Viewer or Editor access with separate logins | Collaborator logins with full permissions, managed on the web |
| Free plan | Yes, with manual accounts | Yes, 2 manual accounts and a 6 month projection |
| Paid price | $10.99 NZD a month or $99 NZD a year | From $119.88 NZD a year on Foundation |
What is the main difference between Fireball and PocketSmith?
PocketSmith is a forecasting tool. You schedule income, bills and budgets on a calendar, and it projects your account balances months or decades ahead. It is powerful and flexible, and you decide what the forecast means.
Fireball combines everyday budgeting with a longer term financial independence plan. You can choose how detailed your budget should be, use categorisation assistance to reduce repeated sorting, and connect your spending and savings to a FIRE projection when you want one.
Which budgeting style can you use?
Fireball offers three budget modes, so you can start with the amount of detail that feels useful:
- Single: one overall spending limit for the period. This suits you if you want to keep an eye on the total without setting a limit for every category.
- Category: separate limits for areas such as groceries, transport and eating out. This suits you if you want to see exactly where spending is running ahead of your plan.
- Flex: one flexible spending amount after your regular and occasional budgets, required transfers, goal reserves and savings targets. This suits you if you want to protect commitments first, then manage the rest together.
You can also turn on zero based planning to give your income a purpose across spending, saving and investing. Weekly, fortnightly and monthly periods let you organise the budget around how you are paid, and you can change modes in Budget settings.
For example, you might start with Single to understand your overall spending. If groceries and eating out need closer attention, use Category. If you mainly want to know what is left after bills and other planned commitments, explore Flex. You do not have to use the FIRE tools to benefit from these budgets.
PocketSmith also supports different budgeting approaches, including envelope and zero based methods. Fireball’s distinction is its explicit choice of Single, Category and Flex modes within the app; PocketSmith offers customisable budgets and a calendar based forecasting workflow.
Will you spend less time categorising transactions?
Fireball is designed to reduce repeated sorting. Your category rules apply automatically, confirmed categories can inform later suggestions, and merchants shared by members and checked by the Fireball team can arrive categorised. When more context is needed, AI can suggest a category for you to review. AI suggestions are part of Paid, require consent and are subject to usage limits.
For example, if your regular supermarket purchases belong under Groceries, you can create a rule for that merchant instead of correcting each purchase. Review unusual purchases separately, especially when one shop sells several kinds of things. AI suggestions do not change a category until you approve them.
PocketSmith also has bank feed categorisation, category rules and filters. Both apps can automate routine work. Fireball brings your rules, confirmed history, reviewed merchant information and optional AI assistance into the same workflow, so you can focus more on exceptions. The time saved depends on your transactions and setup.
Which is better for FIRE and early retirement planning?
Fireball includes dedicated FIRE target and retirement date calculations. PocketSmith’s published tools focus on account forecasts and scenarios, which you can use to explore a retirement plan. Its feature overview does not list a dedicated FIRE number or date calculator.
Fireball shows your target number, projected date, target age and years remaining, and updates them as your accounts change. It tracks standard, Lean, Fat, Coast and Barista FIRE. You can adjust savings, retirement spending or target age, then test how often standard FIRE stays funded across 5,000 possible market outcomes. An After retirement mode shows your withdrawal rate and the monthly spending your investments are estimated to support.
These results are planning estimates, not guarantees or advice.
Which handles KiwiSaver and NZ Super better?
Fireball models KiwiSaver access and NZ Super assumptions within its FIRE projection. PocketSmith can include a KiwiSaver balance in your accounts and forecasts, but its published feature overview does not describe the same dedicated New Zealand retirement model.
Fireball models KiwiSaver, including when you can access it, alongside your other investments and NZ Super assumptions. That gives a more realistic picture for New Zealanders, because KiwiSaver is usually locked until 65 and NZ Super covers part of retirement spending.
Which is better for forecasting?
PocketSmith offers longer calendar based account forecasts: its plan comparison lists six months on Free, 10 years on Foundation, 30 years on Flourish and 60 years on Fortune. You enter or maintain future budgets and income to explore how they affect projected balances.
Fireball forecasts eligible connected account balances 3 to 30 days ahead, shows upcoming bills and income, and projects your long term wealth inside the FIRE plan. If you want to schedule every future transaction years ahead, PocketSmith is the stronger tool.
How do they show what is safe to spend?
Fireball’s Safe to Spend estimates what remains before your next payday after the bills, goal reserves and chosen debt payments included in your budget. Check the amounts and dates behind the estimate, especially when a payment changes.
PocketSmith’s Safe Balance guide says the beta feature adjusts today’s balance for selected budgets already in progress. A future budget is not included in today’s Safe Balance, but you can inspect the forecast on the date it starts. This is a difference in how the figures are calculated, rather than an absence of bill forecasting.
Example: a power bill due before payday
Imagine you have NZ$900 today, with NZ$500 for rent and a NZ$120 power bill due before your next pay. Those two commitments leave NZ$280 before groceries, transport and any other reserves. This is an illustrative example.
In Fireball, review the detected payments and include the relevant commitments in your budget, then check Safe to Spend and the account forecast. The estimate depends on complete and accurate inputs.
In PocketSmith, schedule the rent and power bill on the calendar and check your forecast balance on their due dates. If the power budget has not started yet, PocketSmith’s guide says it will not reduce today’s Safe Balance. The future forecast is where you check that commitment.
Which has the better mobile app?
Fireball brings budgeting, Safe to Spend, FIRE planning, property, debt and shared finances into its iPhone and Android app, with a web app as well. If you mainly manage money on your phone, compare the specific tasks you need rather than assuming both mobile apps have the same scope.
PocketSmith describes Sidekick as a mobile companion to its web app. Check its current mobile features against your needs, particularly if you want to configure forecasts or manage shared finances away from a computer.
How do they handle mortgages and property?
Both track property and mortgages in your net worth.
PocketSmith can include property, debt and mortgage payments in your financial picture. When building the forecast, check how loan balances, repayment budgets and interest assumptions are represented, so a projected account balance is not mistaken for a retirement spending plan.
Fireball links a property to its mortgage, models repayments and interest, and keeps equity in the home you live in separate from the investable wealth that funds your FIRE plan. Joint accounts can be counted at your share.
Which has better AI features?
They take different approaches.
Fireball Paid includes Ask Fireball, a chat assistant that answers questions about your own finances, plus AI category suggestions and an optional Weekly Review. You do not need a separate AI subscription. AI consent and usage limits apply.
PocketSmith has no chat inside the app. Its MCP server lets you connect your account to Claude, ChatGPT or another compatible assistant, which you subscribe to separately, with read only or full access.
How much do Fireball and PocketSmith cost?
| Plan | Price in NZD | What it includes |
|---|---|---|
| Fireball Free | $0 | Manual accounts, budgeting and basic FIRE planning |
| Fireball Paid | $10.99 a month or $99 a year | Unlimited supported bank sync, full FIRE planning, Markets, AI and shared access |
| Fireball Family | $16.99 a month or $149 a year | Full Fireball for five people in total |
| PocketSmith Free | $0 | 2 accounts and a 6 month projection |
| PocketSmith Foundation | $14.95 monthly or $9.99 per month billed annually | 6 banks from one country, 10 year projection |
| PocketSmith Flourish | $24.95 monthly or $16.66 per month billed annually | 18 banks from any country, 30 year projection |
| PocketSmith Fortune | $39.95 monthly or $26.66 per month billed annually | Unlimited banks, 60 year projection |
Compare PocketSmith’s current plans with Fireball’s current pricing before subscribing. PocketSmith’s billing currency guide says New Zealand accounts are billed in NZD; its public pricing page may show another currency based on location. Confirm the currency and full annual charge at checkout.
PocketSmith advertises a 14 day money back guarantee. Eligible new Fireball web customers may receive a 14 day Paid trial. Fireball’s first web subscription charge refund offer is subject to its current guarantee terms and eligibility.
Can couples and families share Fireball or PocketSmith?
Yes, both.
PocketSmith’s collaborator guide says invited users have full permissions and use the web app to manage the shared account. Fireball instead offers Viewer or Editor access, with owner controls for bank connections, billing and security.
Fireball lets you invite trusted people with their own verified logins and choose Viewer or Editor access. A Viewer can see your shared finances, and an Editor can update ordinary records. Bank connections, billing and security stay with the owner. Sharing works on the phone as well as the web.
Can I move from PocketSmith to Fireball without losing my history?
Yes. Fireball imports a PocketSmith export in ZIP, CSV or TSV format and brings across your accounts, transactions, notes, labels and category rules.
If you have already connected your bank in Fireball, you can add your older PocketSmith history to that account. Fireball adds only the transactions from before your bank feed begins, so nothing is counted twice. You review possible duplicates before saving, and you can undo the whole import from Import history. PocketSmith budgets, attachments and unsupported rule settings are not imported.
Follow the step by step guide: Moving from PocketSmith to Fireball.
What should you check during the PocketSmith or Fireball trial?
Try the same payday and upcoming bills in each app. Check whether you can understand the forecast, find the tasks you need on your phone, and keep the figures current without more work than you want. In PocketSmith, test the calendar and scenarios you expect to use. In Fireball, review the detected income and payments, then check the assumptions behind your FIRE projection.
Should you choose Fireball or PocketSmith?
Choose PocketSmith if:
- You want to forecast every account years or decades ahead on a calendar.
- You have banks in several countries.
- You enjoy configuring detailed budgets and scenarios on a computer.
Choose Fireball if:
- You live in New Zealand and want a FIRE number and date calculated for you.
- You want KiwiSaver, NZ Super and your mortgage built into the plan.
- You mostly manage money on your phone.
- You want unlimited bank sync and built in AI without choosing a higher tier.
For a side by side feature table, see Fireball as a PocketSmith alternative.
Common questions
Is PocketSmith a New Zealand company?
Yes. PocketSmith was founded in New Zealand and serves customers around the world. New Zealand customers are billed in New Zealand dollars.
Is Fireball a good PocketSmith alternative?
Fireball suits New Zealanders who want a simpler setup, a full mobile app and a FIRE plan that calculates their number and date with KiwiSaver and NZ Super. If you need long range calendar forecasting or banks in several countries, PocketSmith remains a strong choice.
Is Fireball cheaper than PocketSmith?
Fireball Paid is listed at NZ$99 annually with unlimited connections to supported institutions. PocketSmith’s Foundation, Flourish and Fortune plans have different bank limits and forecast lengths. Compare your required tier, billing currency and full annual checkout total rather than comparing the cheapest plan names alone. Both apps offer a Free plan.
Does PocketSmith calculate a FIRE number?
PocketSmith’s published features describe general cash flow forecasts and scenarios, rather than a dedicated FIRE number calculator. Fireball calculates a FIRE target and projected date from your inputs and assumptions. Both require you to review the information behind the result.
Can I import my PocketSmith data into Fireball?
Yes. Upload your PocketSmith export and Fireball brings across accounts, transactions, notes, labels and category rules. Budgets and attachments are not imported, and you can undo the import at any time.
Does PocketSmith have a full mobile app?
PocketSmith has iPhone and Android apps, but it describes them as companions to the web app, with selected features. Fireball's full planning experience works on the phone.
Is it safe to connect my bank to Fireball?
Fireball uses Akahu for read only access, so it cannot move money or make payments, and it never stores your bank password. Read how Fireball uses your bank data for the details.
Summary
PocketSmith suits people who want to build detailed calendar forecasts and explore account balances over longer periods. Fireball suits New Zealanders who want everyday budgeting alongside dedicated FIRE planning on their phone or the web. Choose based on the forecasting detail, mobile tasks and retirement planning you actually need.
Prices checked 19 October 2026. Fireball publishes this comparison and is included in it.
Make the next money decision calmer
Turn what you just read into a plan you can track, adjust, and actually live with. Explore our free financial calculators or see how Fireball brings your finances together.